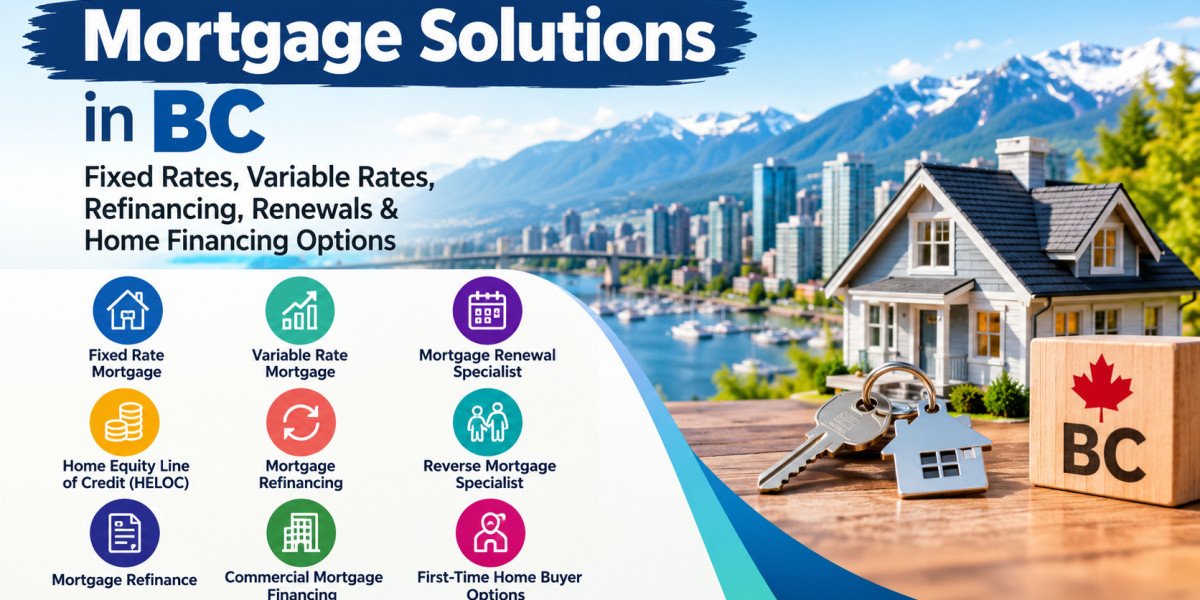

Choosing the right mortgage in British Columbia requires careful planning, an understanding of available loan products, and a realistic view of your financial goals. Whether you are buying your first home, renewing an existing mortgage, refinancing a property, or exploring commercial real estate financing, comparing your options can help you make an informed decision.
Homeowners often compare a Fixed rate mortgage BC with a Variable rate mortgage BC to understand how interest rates may affect their payments. Others seek guidance from a Mortgage renewal specialist BC, explore a Home equity line of credit (HELOC) BC, or investigate Mortgage refinancing BC to manage changing financial needs.
This guide explains the major mortgage options available in British Columbia, what to consider before applying, and how to prepare for your next mortgage decision.
1. Understanding Fixed Rate Mortgage BC Options
A Fixed rate mortgage BC borrowers select generally provides an interest rate that remains unchanged during the agreed mortgage term. This can make budgeting easier because the contracted rate does not fluctuate with market interest rate movements during that period.
Fixed-rate mortgages may appeal to homeowners who want predictable interest costs and greater certainty when planning their household finances.
Benefits of a Fixed-Rate Mortgage
Some potential benefits include:
Predictable interest rate: The contracted rate generally stays the same during the term.
Budgeting confidence: Stable interest costs can make financial planning easier.
Protection from market rate increases: Changes in market rates generally do not alter your contracted rate during the term.
Clearer payment planning: You can plan other household expenses around your mortgage obligations.
However, your total housing expenses may still change because property taxes, insurance, strata fees, and maintenance costs can increase.
What Should You Compare?
When reviewing a Fixed rate mortgage BC product, compare the interest rate, term, amortization period, prepayment privileges, portability, fees, and penalties for ending the agreement early.
A mortgage with a slightly higher rate may offer useful flexibility, while a lower-rate product may have restrictions that are unsuitable for your plans.
2. Exploring Variable Rate Mortgage BC Products
A Variable rate mortgage BC borrowers consider typically has an interest rate that can change according to the lender's pricing and a benchmark such as the lender's prime rate.
Depending on the mortgage structure, an interest rate change may affect your regular payment or the proportion of each payment allocated to interest and principal.
Potential Advantages of Variable Rates
Variable-rate mortgages may appeal to borrowers who are comfortable with changing rates and want to evaluate the potential benefits of interest rate decreases.
Depending on the product, potential advantages can include:
The opportunity to benefit when the applicable rate decreases.
Different early-break penalty arrangements compared with some fixed-rate products.
Mortgage features that may suit particular financial circumstances.
These advantages are not guaranteed. Rates can rise, increasing borrowing costs or affecting repayment timelines.
How to Decide Between Fixed and Variable Rates
When comparing a Fixed rate mortgage BC with a Variable rate mortgage BC, ask yourself:
Can my household budget handle higher interest costs?
How long do I expect to keep the mortgage?
Do I prioritize predictable payments or accept rate uncertainty?
What penalties apply if I sell or refinance early?
Which repayment features matter most to me?
The right mortgage depends on your financial situation and the actual terms offered by the lender.
3. Preparing for Renewal With a Mortgage Renewal Specialist BC
A mortgage renewal is an opportunity to review your existing financing before entering a new term. A Mortgage renewal specialist BC homeowners consult can help explain renewal offers, compare available terms, and identify questions to ask before signing an agreement.
Renewal deserves attention because your financial circumstances may have changed since you first obtained the mortgage.
Why Review Your Mortgage Before Renewal?
During your current mortgage term, your income, expenses, savings, and financial priorities may have changed. Reviewing your mortgage gives you an opportunity to assess whether the existing arrangement remains suitable.
Consider the following:
Compare the renewal offer with other available products.
Review your outstanding mortgage balance.
Check your remaining amortization period.
Evaluate prepayment privileges and penalties.
Consider whether changing lenders is worthwhile.
Explore refinancing if your borrowing needs have changed.
When Should You Start?
Beginning your review several months before maturity gives you time to gather documents and compare offers.
A Mortgage renewal specialist BC homeowners work with may help them understand the differences between renewing with their current lender and switching to another lender. Eligibility and available terms depend on the individual borrower and lender requirements.
4. Using a Home Equity Line of Credit (HELOC) BC
A Home equity line of credit (HELOC) BC homeowners may qualify for is a revolving credit facility secured by their property. It allows approved borrowers to access funds within a set credit limit, subject to the lender's conditions.
A HELOC may be considered for eligible renovations, certain major expenses, or other permitted borrowing purposes.
How Does a HELOC Work?
A lender assesses factors such as property value, existing mortgage debt, income, credit history, and other financial commitments.
If approved, you can generally borrow funds as needed within the credit limit. Interest is usually charged on the amount borrowed, and many HELOC products have variable rates.
Benefits and Risks
A HELOC can provide flexibility, but it also increases the debt secured against your home. Changes in interest rates may increase the cost of borrowing, and failure to meet repayment obligations can put your property at risk.
Before applying for a Home equity line of credit (HELOC) BC product, compare its rate, fees, credit limit, repayment conditions, and relationship with your existing mortgage.
Borrow only after considering whether the funds are necessary and how you will repay them.
5. Exploring Mortgage Refinancing BC
Mortgage refinancing BC homeowners consider may involve replacing an existing mortgage or changing important terms, such as the loan amount, interest rate, or repayment structure.
Refinancing can be useful when your financial goals change, but it should be assessed based on the complete cost of the transaction.
Common Reasons for Refinancing
Homeowners may explore refinancing to:
Access some of their available home equity.
Consolidate certain higher-interest debts.
Fund eligible renovations.
Change their mortgage term or repayment structure.
Adjust their borrowing arrangements after a major life change.
Calculate the Total Cost
Before proceeding with Mortgage refinancing BC, review potential early-break penalties, legal fees, appraisal costs, discharge fees, and lender charges.
A lower monthly payment does not necessarily mean a lower overall cost. Extending the amortization period may reduce the required payment but increase the total interest paid over time.
Compare the proposed mortgage with your existing agreement and other alternatives before making a decision.
6. Learning About a Reverse Mortgage Specialist BC Can Explain
A Reverse mortgage specialist BC homeowners consult can explain how reverse mortgages work, who may qualify, and how costs and repayment conditions can affect home equity.
Reverse mortgages are generally designed for eligible older homeowners who want to access some of their property's equity without making regular principal-and-interest payments in the same way as a conventional mortgage.
Potential Uses of Reverse Mortgage Funds
Depending on eligibility and individual circumstances, homeowners may consider a reverse mortgage to supplement retirement income, cover home-related expenses, or meet other permitted financial needs.
The available amount depends on factors such as age, property value, property type, and lender requirements.
Important Considerations
Before proceeding, understand:
How interest accumulates.
What setup and ongoing fees apply.
When the loan becomes repayable.
How the outstanding balance may grow.
How the arrangement affects remaining home equity.
What implications it may have for estate planning.
A Reverse mortgage specialist BC homeowners speak with should explain the product's conditions and limitations. Independent legal or financial advice may also be helpful before signing.
7. Comparing Mortgage Refinance BC Options
Searching for Mortgage refinance BC solutions can help homeowners understand the available ways to restructure their current mortgage or access property equity.
However, refinancing is not always the best solution. The decision depends on the new terms, the costs of changing your existing mortgage, and your ability to manage the revised debt.
Questions to Ask Before Refinancing
Before selecting a mortgage refinance option, ask:
What will it cost to end the current mortgage?
Will the new rate and terms provide meaningful benefits?
Will I be borrowing more against my property?
How will the new amortization affect total interest costs?
Could renewing at maturity or using another credit product be more suitable?
Preparing Your Application
Lenders may request current mortgage statements, income verification, employment details, bank statements, debt information, and property records.
Having these documents ready can help you compare Mortgage refinance BC options and understand the lender's requirements.
8. Understanding Commercial Mortgage Financing BC
Commercial mortgage financing BC may help eligible business owners and property investors purchase, refinance, or finance commercial real estate.
Commercial mortgage applications often involve a broader assessment than residential mortgages. Lenders may examine the property's income, operating expenses, lease agreements, borrower finances, and the property's intended use.
Types of Commercial Properties
Depending on lender criteria, eligible properties may include:
Office buildings.
Retail properties.
Industrial and warehouse buildings.
Mixed-use properties.
Certain multi-unit rental properties.
Other income-producing commercial real estate.
What Do Commercial Lenders Consider?
Commercial lenders may assess property value, rental income, operating expenses, lease stability, available equity, business financial statements, and debt-service coverage.
Before applying for Commercial mortgage financing BC, prepare relevant financial records and property documents. Compare interest rates, fees, repayment terms, security requirements, and early-repayment conditions.
Evaluate whether the property's expected income can reasonably support its mortgage and operating expenses.
9. Reviewing Mortgage Options for First-Time Home Buyers BC
Buying your first home is a major financial commitment. Exploring Mortgage options for first-time home buyers BC can help you understand down payment requirements, borrowing capacity, mortgage products, and the costs of homeownership.
Start With Affordability
Review your income, savings, credit history, outstanding debts, and monthly expenses before setting a property budget.
Remember to include property taxes, insurance, utilities, maintenance, closing costs, and strata fees where applicable.
Consider Mortgage Pre-Approval
A pre-approval can provide an initial estimate of how much you may be able to borrow. It can help establish a realistic price range before you make an offer.
However, pre-approval is not a guarantee of final approval. The lender may still need to verify your financial information and assess the property.
Compare Your Options
When exploring Mortgage options for first-time home buyers BC, compare:
Fixed and variable interest rates.
Mortgage terms and amortization periods.
Down payment requirements.
Mortgage default insurance, where applicable.
Prepayment privileges and early-break penalties.
Payment frequency and affordability.
Eligibility for applicable government programs.
Program requirements can change, so confirm current eligibility rules and conditions through official sources.
10. Tips for Choosing the Right Mortgage in BC
Selecting a suitable mortgage requires more than finding the lowest advertised interest rate. A structured review can help you understand the costs, risks, and features of each option.
Step 1: Identify Your Goal
Determine whether you are buying a home, renewing a mortgage, refinancing, accessing equity, or financing commercial property.
Step 2: Review Your Financial Position
Consider income stability, savings, credit history, debts, and your ability to manage higher payments if interest rates change.
Step 3: Compare Lenders and Products
Compare rates, fees, repayment conditions, portability, prepayment privileges, and penalties. Make sure you are comparing similar mortgage terms.
Step 4: Calculate the Total Cost
Consider the interest rate, loan amount, amortization period, and applicable fees. A lower monthly payment may not mean a lower total cost.
Step 5: Understand the Contract
Read the agreement carefully and ask questions about any conditions you do not understand. Make sure the payment structure and repayment obligations suit your financial circumstances.
Frequently Asked Questions About Mortgage Solutions in BC
What is the difference between a fixed and variable mortgage?
A fixed-rate mortgage generally keeps the contracted interest rate unchanged during the term, while a variable-rate mortgage can change according to its terms. Your financial circumstances and tolerance for risk should guide your choice.
When should I contact a Mortgage renewal specialist BC?
It is helpful to start reviewing your options several months before your mortgage maturity date. This gives you time to compare renewal offers and consider whether switching lenders is worthwhile.
What is a Home equity line of credit (HELOC) BC?
A HELOC is a revolving credit facility secured by your home. Approved borrowers can access funds within a credit limit, subject to lender terms and repayment requirements.
Is Mortgage refinancing BC always beneficial?
No. Refinancing may support certain financial goals, but penalties, fees, and changes in borrowing costs can reduce the benefits. Calculate the total cost before proceeding.
What does a Reverse mortgage specialist BC explain?
A reverse mortgage specialist can explain eligibility, interest accumulation, fees, repayment conditions, and the potential effect on your home equity.
How can I compare Mortgage refinance BC options?
Compare interest rates, fees, early-break penalties, amortization periods, repayment conditions, and the total expected borrowing cost. Consider whether renewal or another credit product might be more appropriate.
Who may qualify for Commercial mortgage financing BC?
Eligibility depends on the lender, property type, borrower finances, available equity, rental income, and other underwriting requirements.
What should first-time buyers consider when comparing mortgage options?
First-time buyers should review affordability, down payment requirements, mortgage insurance where applicable, closing costs, interest rates, and repayment features before committing to a property.
Conclusion: Plan Your Mortgage Strategy With Confidence
Choosing the right mortgage in British Columbia starts with understanding your financial needs and comparing the available products carefully.
A Fixed rate mortgage BC may appeal to borrowers who value predictable interest costs, while a Variable rate mortgage BC may suit those who can manage rate uncertainty. Homeowners approaching maturity can review their options with a Mortgage renewal specialist BC, while those seeking access to equity may compare a Home equity line of credit (HELOC) BC with Mortgage refinancing BC and Mortgage refinance BC options.
Eligible older homeowners may also investigate the implications of working with a Reverse mortgage specialist BC. Business owners and property investors can explore Commercial mortgage financing BC, while new buyers can research Mortgage options for first-time home buyers BC to prepare for their purchase.
Before choosing a mortgage, compare the complete cost, repayment terms, eligibility requirements, and potential risks. A well-informed decision can help you select financing that better fits your goals and financial circumstances.
Explore More Mortgage Guides in BC
Continue learning with these related mortgage topics:
Fixed vs. Variable Rate Mortgage in BC: Understand the differences between fixed and variable interest rates.
Mortgage Renewal Guide for BC Homeowners: Learn how to prepare for renewal and compare lender offers.
Mortgage Refinancing in BC: Explore refinancing costs, benefits, and important considerations.
HELOC Guide for BC Homeowners: Learn how home equity lines of credit work and what risks to consider.
Reverse Mortgages in BC: Review eligibility, costs, and potential effects on home equity.
Commercial Mortgage Financing in BC: Understand key considerations for business owners and property investors.
First-Time Home Buyer Mortgage Guide in BC: Prepare for pre-approval, budgeting, and the mortgage application process.
Add internal links to your published articles using the relevant topic titles above. This helps readers discover related information and makes it easier to navigate your website.
Disclaimer: This article is for general informational purposes only and does not constitute financial, legal, tax, or mortgage advice. Mortgage rates, fees, eligibility requirements, and lending policies may change. Confirm current terms with the relevant lender or qualified professional before making a financial decision.